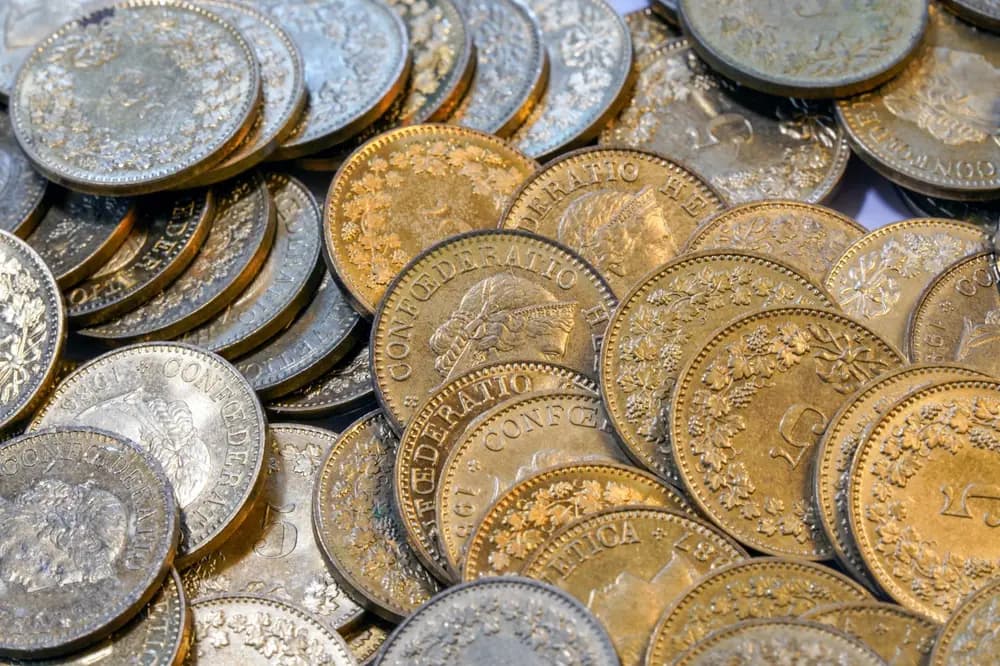
Gold belongs to you. It is still not free.
In short: a bar is not a promise, it is property. It cannot default the way a bank can. In return you pay 2.56% to 3.83% above the pure gold value when you buy, around 6.6% lies between the purchase price and the buy-back price, and storage costs money every year. Investment gold is at least exempt from VAT (§ 25c UStG). This page says what other providers write only in the small print.
Updated on · Michael Jung, Broker specialising in tangible assets
The difference
Why gold at all?
Because it is the only thing in your wealth that is nobody's liability. Your bank balance is a claim against the bank, your life insurance a claim against the insurer, a bond a claim against a state. A bar in the safe is not a claim, it is simply there. That is why it also cannot be drawn into a bail-in.
- ≈ €3,830
- per troy ounce of gold in early September 2026
- ≈ 9.5% a year
- average performance of gold in euros since 1999. Historical, no guarantee for the future.
- § 25c UStG
- Under the German VAT Act, investment gold is exempt from VAT: bars with a fineness of at least 995 thousandths, coins with at least 900 thousandths and minted after 1800. The exemption does not apply to silver.
For context: the ≈ 9.5% a year is a look back since 1999, not a promise for tomorrow. The gold price moves, downwards too, and it pays neither interest nor rent.
The costs
What do you pay above the metal value?
- 100-gram gold bar2.56%
- 1-ounce gold coin (Krugerrand)3.83%
- 1-ounce silver coin (Maple Leaf)39%
The gold price first has to rise 6.6%, before you even break even. Nobody else does that sum for you.
| What | How much | What that means |
|---|---|---|
| Gold coin, 1 ounce | 3.83% | The premium over the pure metal value. You pay it when you buy, and you never see it again. |
| Gold bar, 100 grams | 2.56% | Large units cost less than small ones. In return, a bar cannot be sold in parts. |
| Silver coin, 1 ounce | 39% | Silver starts far below break-even. Anyone buying silver needs patience or a good reason. |
| Buy-sell spread | 6.6% | This is how far the gold price has to rise before you break even. |
| Storage, per year | €200–300 | A precious metals account at a dealer. A bank safe-deposit box starts at €31 a year, an international vault platform at 0.12% of the value. |
| VAT | § 25c UStG | Investment gold is exempt from VAT. Silver is not, so there the tax comes on top of the premium. |
Market values, not offers. Premium and spread move with the market. The date is shown with every figure. Not investment advice.
Storage
Where should it be kept?
With a safe-deposit box, most people look at the annual rent. Another figure matters more. When 3,256 safe-deposit boxes were broken open in Gelsenkirchen in 2025, the Sparkasse replaced at most €10,300 per box under its rental agreement.
- €10,300
- Maximum the Sparkasse reimburses per safe-deposit box (under the rental agreement)
- €200–300
- Precious metals account at a dealer, per year. A bank safe-deposit box starts at €31 a year, an international vault platform at 0.12% of the value, at least 48 US dollars.
So the question is not “how secure is the vault” but “up to what amount is anyone liable”. That figure is in the contract, and you are allowed to ask for it before you sign.
Silver
And silver? The same principle, quite different figures.
The VAT exemption under § 25c UStG applies only to investment gold, not to silver. Together with the higher trading costs, that leads to a premium of 39% on a silver coin and 31% on a one-kilo bar. So anyone buying silver starts around a third below break-even. It can be worth it, but only over very long periods, and someone should say so beforehand.
What you can do
Three rules that save a lot of money.
01
Large units
The smaller the piece, the higher the premium. Given the choice, buy one 100-gram bar rather than ten ten-gram bars, unless being able to sell in parts matters more to you than the price.
02
Settle the storage first
Not the purchase first and the storage afterwards. With a safe-deposit box or a dealer account, the contract decides how much is replaced if something happens. That figure is rarely in the brochure.
03
Only money that can sit still
Buying and selling back cost around 6% together. Money that is needed in two years does not belong in gold. Money that can sit still for twenty years can carry that spread.
Since 2016/17 Michael Jung has been a certified precious metals advisor (Edelmetallberater, GG-Akademie Berlin) and goes through selection, unit sizes and storage with you before you buy. More on that under Services. What inflation does to the money that is not in tangible assets is under Inflation and purchasing power.
This is where we buy gold + silver
storage free of charge included
Common questions
Answered briefly.
Is gold exempt from VAT?
Investment gold is: under § 25c of the German VAT Act (UStG), the supply of bars with a fineness of at least 995 thousandths and of coins of at least 900 thousandths, minted after 1800, is exempt from VAT. The exemption does not apply to silver. That is one of the reasons for the high premium on silver.
How much gold makes sense?
There is no answer that holds for everyone, and anyone who names a percentage without knowing your assets is guessing. The useful question is the other way round: which part of your wealth is today a claim against someone (a bank balance, a life insurance policy, a bond), and how much of it should be something you own?
At home, safe-deposit box or dealer account?
All three have a catch. At home costs nothing, but your contents insurance replaces valuables only up to a limit. With a bank safe-deposit box it is not the rent that counts but the maximum amount in the contract: in Gelsenkirchen, after the break-in in 2025, the Sparkasse replaced only €10,300 per box. An account at a dealer costs €200 to €300 a year, and insurance is usually included.
Read on
More about your wealth. Short, with sources.
Asset protection
Five things about money that almost everyone believes.
Bank, inflation, insurance, the state and inheritance, fact-checked with law and source.
Read more
Bank failure & deposit protection
From the 100,001st euro, you have no legal claim.
The Volksbank Brawo case, bail-in, and how much of your balance is protected.
Read more
Inheritance tax 2026
Your tax-free allowance has been frozen since 2009.
What the court in Karlsruhe reviews in October, and how much tax your heirs would pay.
Read more
Life insurance
Guaranteed does not mean untouchable.
§ 314 VAG, § 222 VAG and a protection fund of one per mille. With a benefit-cut calculator.
Read more
Wealth levy
The Lastenausgleich is history. The article in the constitution is not.
What really happened in 1952, what the DGB is demanding in 2026, and what both have to do with you.
Read more
Inflation & purchasing power
Two percent sounds harmless. After twenty years, it is a third.
What is left of your savings in 5 to 30 years, with interest taken into account.
Read more
Buy gold
This is where we buy gold and silver. Storage free of charge.
Physical metal from €50 through NOVEM Gold, insured in a vault. With a calculator: what do you need for €1,000 more pension?
Read more
Property in Florida
A house in Florida. First the big picture, then the details.
Property in US dollars · newly built in the north of Cape Coral · costs, taxes and renting at a glance.
Read more
US company
Your own company in the USA. A foothold outside Germany.
Registered online, with an account in dollars. With a step-by-step roadmap and the real costs.
Read more
US account
250,000 dollars protected instead of 100,000 euros.
What US deposit insurance covers, how much of your savings would be protected and how the appointment in Florida works.
Read more
Deposit protection calculator
How much of your money is really protected?
Several banks, joint accounts and the six-month case, calculated in one go. Result as a link or on paper.
Read more
Inheritance tax calculator
What will your heirs keep?
All heirs with their shares, and the family home you live in. Result as a link or on paper.
Read more
Written and reviewed by
Michael Jung
Broker specialising in tangible assets · Insurance broker
- 1996Certified Insurance Specialist (Geprüfter Versicherungskaufmann, IHK)
- 2003Certified Finance Specialist (Geprüfter Finanzwirt, bbw)
- 2005Master Consultant in Finance
- 2016–17Senior Consultant, precious metals advisor (Edelmetallberater, GG-Akademie Berlin)
- 2021Certified under DIN 77230, the German standard for financial analysis (DEFINO)
- 2023Florida Premium Real Estate certification
Insurance broker licensed under § 34d GewO · German register of intermediaries D-5D7P-3694H-28 · Last reviewed on
Free initial consultation
How much of your wealth do you own, and how much is only a promise?
Michael Jung goes through it with you and sets out the costs honestly before you buy anything. Free and without obligation.
Consultations in German and English.