Michael Jung · Asset protection with tangible assets
How do you want to live ten years from now?
And how much of your wealth will still be yours then?
AI-generated film scenes
AI-generated film scenes
The problem
Four risks to your wealth. Which one would you like to understand better?
Your account
Your balance shows euros. Not what you can buy with them.
If prices rise faster than your savings grow through interest, you lose purchasing power.
2.9%
Inflation in August 2026 compared with August 2025
1.95%
Interest on instant-access savings, on average
−37%
Purchasing power of the euro since 2001
What rising prices mean in everyday life
Ten-year comparison: annual average 2015 against 2025
- Fruit
- +41.6%
- Vegetables
- +44.4%
- Food and non-alcoholic beverages overall
- +49.2%
A comparable fruit shop that cost €100 in 2015 cost about €142 in 2025. For vegetables it was about €144.
Total increase over ten years, not an annual inflation rate. Our own calculation from the index levels, 2020 = 100.
Your personal inflation rate: calculator of the Federal Statistical Office (in German) ↗What would €10,000 have become?
€10,000 in 2015, and what would have become of it by today, depending on where the money went:
In a passbook savings account
€10,586
The money stays where it is and earns the interest that was usual at the time. The bare account balance, without price rises set against it.
Purchasing power of that balance
€7,560
The amount stays the same as a figure, but prices rise. This line shows what is left of it in real terms.
Moved into gold
€39,202
The amount is exchanged for troy ounces of gold in the start year and valued today at the current gold price.
€10,000 from 2015 until today: about €10,586 in a passbook savings account, about €7,560 left in real terms, about €39,202 in gold.
What does that mean for your wealth? Just ask:+49 170 7676706Free of charge, no appointment needed. Consultations in German and English.
A simplified model calculation based on public time series. Past performance says nothing about the future. Not investment advice.
Your bank balance
How safe is €100,000 in the bank?
Eligible deposits generally come with a statutory right to compensation of up to €100,000 per person, per bank. Several accounts at the same bank are added together. In certain cases set out in law, higher protection applies for a limited time.
Covered deposits are expressly excluded from bail-in. For balances above that, it depends on further protection schemes and the specific situation.
What deposit protection does not protect is the purchasing power of your money.
€100,000
statutory right, per person, per bank
voluntary
is the protection above that, with no enforceable right
§ 91 SAG
Bail-in since 2015, covered deposits excluded
It has happened before. September 2026: Volksbank Brawo has to be propped up with up to €723 million. This time the other banks pay.
Your life insurance
“My life insurance pays out, guaranteed.” Not always.
If a life insurer is permanently unable to meet its obligations, the supervisory authority can, under the conditions set out in law, temporarily stop payments and reduce contractual benefits. § 314 VAG sets no fixed percentage limit for such a cut.
In principle this would also affect unit-linked life insurance, because its investments are part of the insurer's guarantee assets.
§ 314 VAG
Payment freeze and cut, with no fixed limit
up to 5%
Benefit cut, even with the protection fund
10–30%
less company pension at the Caritas pension fund
“Subject to the condition in subsection 1 sentence 1, the supervisory authority may, if necessary, reduce the obligations of a life insurance undertaking under its policies in line with its assets.”
You keep paying your premiums at the previous level during this time.
It has happened before. Element Insurance 2025: insolvency, around 320,000 policies ended.
Property wealth in Germany
Germany's Basic Law provides for one-off wealth levies as a type of tax.
Under the Lastenausgleich of 1952, Germany's post-war burden-sharing levy, the wealth levy was 50 percent of taxable wealth.
Article 106 of the Basic Law does not introduce a new levy itself. And the valuation rules and allowances of that time cannot be equated with a flat levy on today's market value of a property.
50%
Wealth levy in 1952, in instalments over up to 30 years
Art. 106 GG
Basis for one-off wealth levies
€2,662.2 billion
Public debt at the end of 2025 · €31,887 per resident
Estimated current debt
≈ €3.03 trillion
A modelled live estimate based on Eurostat data, not an official real-time measurement. It uses a different definition from the Federal Statistical Office figure, so do not combine the two. The per-person figure is not a personal liability.
Open the German debt clock ↗Under discussion. In June 2026 the DGB, Germany's trade union confederation, calls for a one-off wealth levy of 10 percent on private net wealth from €10 million.
A demand, not a draft law. A new Lastenausgleich is not currently planned.
Hypothetical scenario for a property worth €500,000
A freely chosen scenario, not a levy in force and not a forecast. It does not fully reproduce the historical Lastenausgleich and does not calculate the DGB demand.
Existing loans are not taken into account.
Assumed levy
€220,000
(€500,000 − €60,000) × 50%
Yearly instalment (annuity)
€12,723
The same amount every year, repayment plus interest, over 30 years at 4% interest.
Per month
€1,060
Monthly average of the yearly payment.
Scenario for a property worth €500,000: an assumed levy of €220,000, on average €1,060 a month over 30 years.
How much of your wealth hangs on one country? Just ask:+49 170 7676706Free of charge, no appointment needed. Consultations in German and English.
AI-generated film scenes
The solution
Germany is your starting point. Not your limit.
- Ownership, not promises.
- More than one location.
Michael Jung's answer
A way through every risk. Three examples of many.
A company of your own in the USA
US LLC + bank account
A company of your own in Florida and an account in US dollars. Michael Jung shows you the way from formation to EIN and ITIN, in German and English.
Against concentration risk in Germany
Property in Florida
A tangible asset, the US dollar and US law in one.
Against bail-in and inflation
Gold and silver
Bars and coins belong to you. They are not a claim against a bank.
Against cuts by your insurer
Independent insurance review
As a broker licensed under § 34d GewO, Michael Jung works for you and checks how stable your insurers are.
Florida, an honest look
In its favour
+196,700
residents in Florida from 2024 to 2025, total growth0%
personal income tax at Florida state level. Federal and other taxes may still apply3.32 million
visitors to Lee County (Fort Myers, Cape Coral, Sanibel) in 2025, 3.8% more than in 2024
What you need to know
$3,576
average annual premium for homeowners insurance including wind cover in Lee County (Cape Coral, Fort Myers), as of 31.03.2026. An average across all insured homes. The actual premium depends on the insurer, the insured value, the deductible and the policy termsseparate
Flooding is not covered by most homeowners policies. It needs a policy of its own, which may be mandatory depending on location and financing6%
Florida state sales tax on rentals of six months or less. Depending on the county, a tourist development tax of 3 to 6% and a county surtax come on top
The full calculation, with insurance, maintenance and vacancy, is on the Florida page.
Michael Jung · for more than 30 years
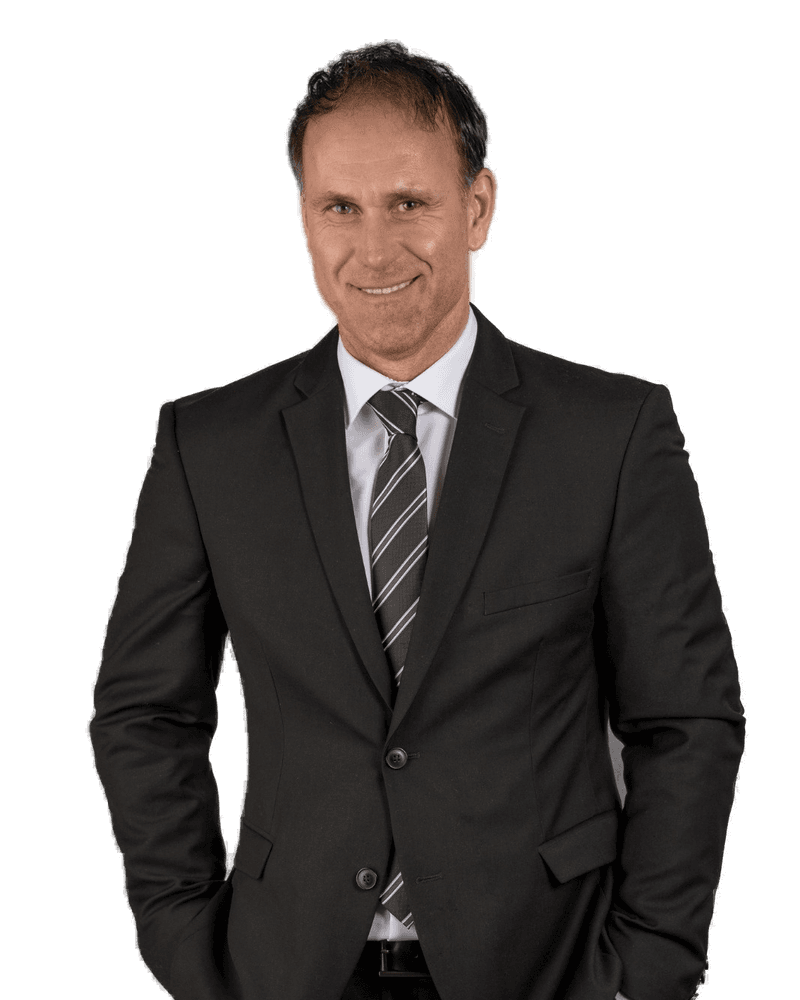
“I advise my clients the way I would like to be advised myself.”
- 1996Certified Insurance Specialist (Geprüfter Versicherungskaufmann, IHK)
- 2003Certified Finance Specialist (Geprüfter Finanzwirt, bbw)
- 2005Master Consultant in Finance
- 2016–17Senior Consultant, precious metals advisor (Edelmetallberater, GG-Akademie Berlin)
- 2021Certified under DIN 77230, the German standard for financial analysis (DEFINO)
- 2023Florida Premium Real Estate certification
View certificates
Insurance broker licensed under § 34d GewO · German register of intermediaries D-5D7P-3694H-28
Career, way of working and licences: About us.
How it works
Three steps. Confidential and without obligation.
01
Initial consultation
Where do you stand, and what matters to you?
02
Analysis
Accounts, contracts, property: where are the risks?
03
Implementation
Gold, property, insurance. Step by step, at your pace.
What we look at in detail is described under Services.
In brief
Frequently asked questions.
What does the initial consultation cost?
Nothing. It is free and without obligation.
Do I have to come to Bielefeld?
No. We can also talk by phone.
Is a new Lastenausgleich coming?
None has been passed or planned. But the basis in Germany's constitution exists, and in 2026 the German Trade Union Confederation (DGB) called for a wealth levy.
Learn more
Everything to read in your own time. With law, source and date.
Asset protection
Five things about money that almost everyone believes.
Bank, inflation, insurance, the state and inheritance, fact-checked with law and source.
Read more
Bank failure & deposit protection
From the 100,001st euro, you have no legal claim.
The Volksbank Brawo case, bail-in, and how much of your balance is protected.
Read more
Inheritance tax 2026
Your tax-free allowance has been frozen since 2009.
What the court in Karlsruhe reviews in October, and how much tax your heirs would pay.
Read more
Life insurance
Guaranteed does not mean untouchable.
§ 314 VAG, § 222 VAG and a protection fund of one per mille. With a benefit-cut calculator.
Read more
Wealth levy
The Lastenausgleich is history. The article in the constitution is not.
What really happened in 1952, what the DGB is demanding in 2026, and what both have to do with you.
Read more
Inflation & purchasing power
Two percent sounds harmless. After twenty years, it is a third.
What is left of your savings in 5 to 30 years, with interest taken into account.
Read more
Gold & silver
Gold belongs to you. It is still not free.
Premium, spread and storage costs set out openly, including the point at which you break even.
Read more
Buy gold
This is where we buy gold and silver. Storage free of charge.
Physical metal from €50 through NOVEM Gold, insured in a vault. With a calculator: what do you need for €1,000 more pension?
Read more
Property in Florida
A house in Florida. First the big picture, then the details.
Property in US dollars · newly built in the north of Cape Coral · costs, taxes and renting at a glance.
Read more
US company
Your own company in the USA. A foothold outside Germany.
Registered online, with an account in dollars. With a step-by-step roadmap and the real costs.
Read more
US account
250,000 dollars protected instead of 100,000 euros.
What US deposit insurance covers, how much of your savings would be protected and how the appointment in Florida works.
Read more
Services
Four building blocks, one plan.
Gold and silver, insurance, property in Florida and a wealth review: what we actually do for you.
Read more
About us
Over 30 years, one profession.
Who Michael Jung is, how we work and which licences stand behind it.
Read more
Free initial consultation
How much of your wealth should still be yours in ten years?
Office 05206 920896 · info@mj-partner.com
Consultations in German and English.